
Updated November 2026 · 5 min read
A steady accounts receivable follow-up process is often the difference between a profitable SME that struggles for cash and one that can pay its bills on time. In the UAE, long payment terms, post-dated cheques and busy customers are common. As a result, invoices can sit unpaid for months unless someone chases them. This guide sets out a practical process you can run every week, and explains how accounting and bookkeeping services in Dubai can keep it moving when your own team is stretched.
Why Collections Need a Process
Most late payments are not disputes. The invoice went to the wrong person, a purchase order number was missing, or the customer’s finance team simply did not prioritise it. A clear process fixes most of these causes before they turn into bad debts.
Cash flow is the obvious benefit. Every day an invoice stays unpaid, you are financing your customer’s business. For a contracting firm or a distributor with tight margins, a few large overdue balances can force expensive bank borrowing.
There is a tax angle too. Under UAE VAT, you usually pay output tax on an invoice in the period you issue it. This applies whether or not the customer has paid. Slow collections mean you fund the VAT as well as the cost of the goods or services.
Set Clear Credit Terms From the Start
Collections start before the sale. Agree credit terms in writing, such as 30 days from invoice date, and put them on every quotation, contract and invoice. For new customers, ask for a trade licence copy and a credit application. For larger amounts, set a credit limit with management approval.
Get the invoice right the first time. It should show the customer’s correct legal name, address and tax registration number, your bank details, the payment terms and any purchase order reference the customer requires. A rejected invoice restarts the clock.
Send invoices promptly, ideally on the day you deliver the goods or finish the work. Every day of delay in invoicing adds a day to your collection period.
An Accounts Receivable Follow-Up Schedule That Works
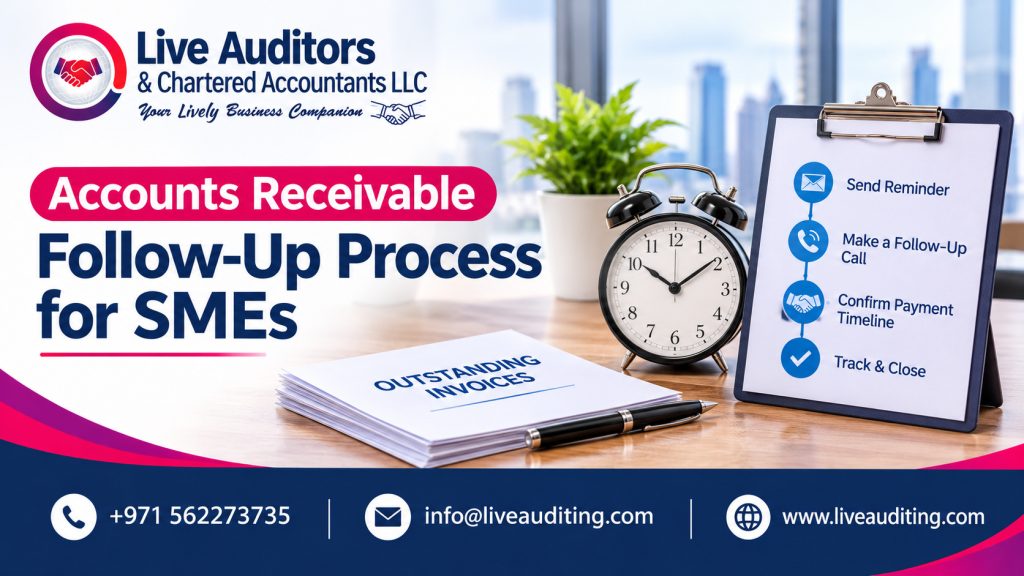
Consistency matters more than tone. A simple schedule that runs every week will collect more than occasional angry calls. A typical approach looks like this:
- A few days before the due date, send a friendly reminder with the invoice attached
- On the due date, confirm the customer has scheduled the payment
- At 7 days overdue, send a firmer email and call the customer’s accounts team
- Once an invoice is 30 days overdue, escalate to your contact’s manager and pause new orders if needed
- At 60 days overdue, issue a formal demand letter
- At 90 days overdue, consider legal or collection options
Keep notes of every call and email against the customer in your accounting system. When someone else picks up the account, they can see exactly what the customer promised.
Adjust the schedule to the customer. A government entity or a large developer may run fixed payment cycles. So learn their cut-off dates and make sure they approve your invoice in time. A small retailer may respond better to a quick phone call than an email. Either way, always end each contact with a specific payment date you can follow up on.
Use Ageing Reports to Focus Effort
An aged receivables report groups unpaid invoices by how long they have been outstanding, usually current, 1 to 30 days, 31 to 60, 61 to 90 and over 90. Run it weekly and review it with whoever owns collections.
Focus first on the largest overdue balances and the oldest invoices. A single AED 200,000 invoice at 75 days needs more attention than twenty small invoices at five days. Watch for customers whose payments are slowly getting later, because that is often the first sign of financial trouble.
Track your days sales outstanding each month. If it rises from 45 to 70 days, something in your process or your customer base has changed. Your auditors will look at the same ageing when they assess whether receivables are recoverable, so clean data also helps with internal and external audit services in UAE.
Handling Disputes, Cheques and Bad Debts
When a customer disputes an invoice, resolve it quickly. Get the specific issue in writing, fix it with a credit note if you agree, and chase the undisputed part separately.
Post-dated cheques are still common in the UAE. Record them in a separate register, deposit them on the correct date and follow up immediately if one bounces. Under current rules, you can generally pursue a returned cheque through the courts’ execution procedures. However, take legal advice before you act.
Some debts will never come back. Provide for doubtful debts in your accounts based on a realistic review, and write off balances once recovery is clearly unlikely. Under UAE VAT, you may be able to reclaim output tax on a bad debt if conditions are met, including the debt being written off in your accounts, at least six months having passed since the payment due date, and the customer being notified. Keep the evidence.
For larger disputes, organisations such as Dubai Chambers offer resources for businesses, including information on commercial mediation and arbitration options.
Make Someone Responsible
Collections fail when they are everyone’s job and therefore nobody’s. Name one person who owns the receivables list, even in a team of five. Give them authority to pause deliveries to overdue accounts and a weekly slot with the owner to review the ageing.
If that person is also the bookkeeper, payroll manager and office administrator, follow-up will slip. That is where outsourced accounting and bookkeeping services in Dubai can help by preparing ageing reports, sending reminders and reconciling customer statements on a fixed schedule.
Turning Invoices Into Cash
Good collections rely on clear terms, accurate invoices, a regular reminder schedule, weekly ageing reviews and a named owner. None of it is hard, but it has to happen every week. If you would like support running the process, our accounting and bookkeeping services in Dubai include receivables management and monthly customer reconciliations.
Contact us on +971 56 227 3735 or email info@liveauditing.com to set up a collections process that keeps cash coming in.
Related reading:
- WPS Payroll Rules Every UAE Employer Should Follow
- How to Set Up a Chart of Accounts for a UAE Company
- Fixed Asset Register and Depreciation for UAE Firms
Frequently Asked Questions
1. What is an accounts receivable follow-up process?
An accounts receivable follow-up process is a set schedule of reminders, calls and escalation steps used to collect unpaid customer invoices. It usually starts before the due date and becomes firmer as an invoice ages. Clear credit terms, accurate invoices and weekly ageing reviews are the foundation of an effective process.
2. How often should I follow up on unpaid invoices?
Follow up shortly before the due date, on the due date, and then at regular intervals such as 7, 30, 60 and 90 days overdue. Review the aged receivables report every week. Consistent, polite contact at fixed points usually collects more money than irregular reminders sent only when cash is tight.
3. What is an aged receivables report?
An aged receivables report lists unpaid customer invoices grouped by how long they have been outstanding, such as current, 1 to 30 days, 31 to 60 days, 61 to 90 days and over 90 days. It shows where you need collection effort most and helps estimate any provision for doubtful debts.
4. Can I recover VAT on bad debts in the UAE?
Yes, UAE VAT allows businesses to recover output tax paid on bad debts if certain conditions are met. These include the goods or services having been supplied and VAT paid, the debt being written off in the accounts, at least six months passing since the due date, and the customer being notified.
5. What is a good days sales outstanding for an SME?
A good days sales outstanding figure is one close to your standard credit terms. If you offer 30-day terms, a figure between 30 and 45 days is generally healthy. A rising figure suggests that collections are slipping or customers are under financial pressure, and it deserves a closer look at the ageing report.
