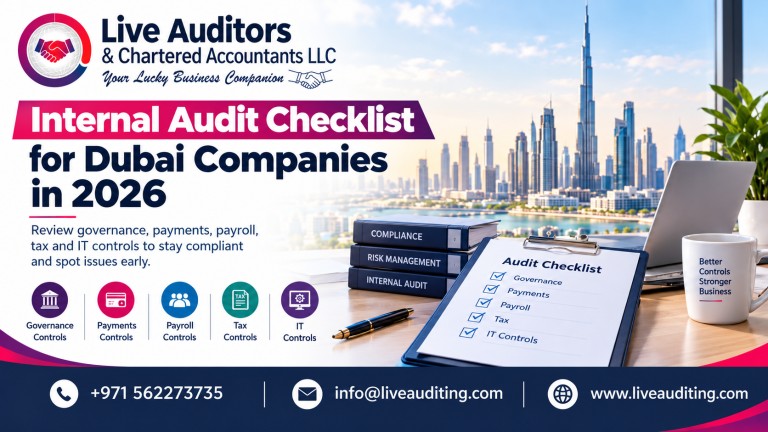
Internal Audit Checklist for Dubai Companies in 2026
Updated October 2026 · 10 min read · liveauditing.com
Most fraud and costly errors start small. A missing approval here, an unchecked supplier there. An internal audit checklist helps you catch these gaps before they grow. This guide gives Dubai companies a practical list for 2026, covering controls, compliance and systems. Whether you run reviews in house or use internal and external audit services in UAE, the same checklist applies.
What an Internal Audit Checklist Covers
An internal audit looks at how your business runs, not only at the numbers. It tests whether controls work, whether staff follow policies and whether risks get attention. Unlike the statutory audit, management decides the scope and timing.
The Institute of Internal Auditors sets global standards for this work. Its guidance stresses a risk-based approach, so you review high risk areas first and more often.
Governance and Risk Assessment
Start at the top. Check that the board or owners approve key policies and review them each year. Then confirm that the business keeps a current risk register.
- Clear delegation of authority for spending and contracts
- An up-to-date risk register with an owner for each risk
- Conflict of interest declarations from managers
- A whistleblowing channel that staff know about
Where a policy or record is missing, note the gap and agree a deadline to fix it.
Finance and Procurement Controls
Next, focus on where money leaves the business. Because payments carry the highest fraud risk, test them closely.
- Segregation of duties between ordering, approving and paying
- A three-way match of purchase order, delivery note and invoice
- Monthly bank reconciliations with a second reviewer
- A log of every change to supplier bank details
- Petty cash counts and expense claim reviews
Also sample a few payments each month and trace them back to approvals. This simple test often reveals weak spots quickly.
Payroll, Inventory and Assets
Payroll errors often go unnoticed for months. So compare your payroll register with WPS records and employee contracts. Also confirm that end of service provisions match UAE labour law.
For inventory, attend at least one surprise count each year. Meanwhile, check that the fixed asset register matches what actually sits in your office or warehouse.
Also review leave balances and overtime approvals. These small items often add up to large unrecorded liabilities by year end, so include them in every cycle.
Tax and IT Items on Your Internal Audit Checklist
Tax deserves its own section of any internal audit checklist. Review VAT returns against sales records and check that your invoices meet FTA rules. Likewise, confirm that your Corporate Tax records will support next year’s return. Support from VAT consultancy services in Dubai can help when the review finds gaps.
Your accounting system also needs attention. Check user access rights, password rules and data backups. If you use TallyPrime, review audit trails and who can edit closed periods. A Tally Prime Dubai partner can tighten these settings for you.
Red Flags Your Review Should Catch
Some warning signs deserve immediate attention. For example, look for duplicate supplier payments, round sum invoices and frequent manual journals near month end. Likewise, check for staff who never take leave, since this can hide ongoing fraud. Sudden margin drops and unexplained stock losses also call for a closer look. When you spot one of these signs, widen the sample and test the full process. Add these checks to your internal audit checklist so every review covers them.
Who Should Own the Internal Audit Checklist?
Ownership decides whether the internal audit checklist actually gets used. In small companies, the finance manager often runs it with support from an outside reviewer. In larger businesses, a dedicated internal auditor or audit committee takes charge.
Whoever owns it needs independence. For instance, the person who approves payments should not audit the payment process. Otherwise, problems stay hidden. Clear reporting lines also matter, so findings reach the owners or board without filtering.
Finally, give the owner a simple tracker. List each finding, its risk level, the agreed fix and the due date. Review this tracker at every management meeting until each item closes.
How to Run Your Internal Audit Checklist in 2026
First, rank each area by risk and plan reviews across the year. Then document every test, the result and the person who will fix each issue. Finally, follow up within 60 days to confirm the fixes work.
Many growing companies lack the time or skills to do this well. In that case, outsourced internal audit services for companies in Dubai give you an independent view without hiring a full team.
Conclusion
A clear internal audit checklist gives Dubai companies early warning on fraud, errors and compliance gaps. Review governance, finance, payroll, tax and IT controls on a regular cycle, then act on what you find. As a result, your statutory audit becomes smoother too. Our internal audit services for companies in Dubai help you build and run this process. Contact us to plan your 2026 internal audit.
Frequently Asked Questions
1. What should an internal audit checklist include?
A good checklist covers governance, risk management, procurement, payments, payroll, inventory, fixed assets, tax compliance and IT controls. Each item should list the test you will run, the evidence you need and the person responsible. Rank areas by risk so you review the most sensitive processes first and more often.
2. Is internal audit mandatory for companies in Dubai?
For most private companies in Dubai, internal audit is not a legal requirement. However, listed companies, banks and some regulated sectors must maintain an internal audit function. Many private businesses still choose it because it reduces fraud risk, improves controls and makes the annual statutory audit faster and cheaper.
3. How often should companies run an internal audit checklist?
Most companies review high risk areas such as payments and payroll every quarter. Lower risk areas can follow an annual cycle. In addition, run a targeted review after major changes, such as a new system, rapid growth or a key staff exit. This keeps controls current as the business evolves.
4. What is the difference between internal and external audit?
An internal audit reviews processes, controls and risks for management, and the business sets its scope. An external audit gives an independent opinion on the financial statements for shareholders, banks and authorities. Both add value, but only the external audit meets licence renewal and Corporate Tax audit requirements.
5. Can a small business outsource internal audit?
Yes. Many small and mid-sized companies outsource internal audit instead of hiring full-time staff. An outside firm brings trained auditors, proven checklists and an independent view. You pay only for the reviews you need, which makes it a cost effective option for businesses with limited finance teams.