
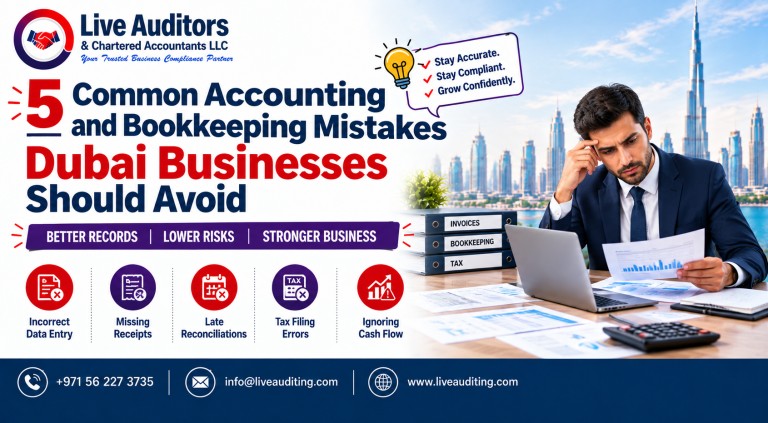
5 Common Accounting and Bookkeeping Mistakes Dubai Businesses Should Avoid
Updated September 2026 · 10 min read · liveauditing.com
Running a business in Dubai means juggling VAT deadlines, corporate tax obligations, supplier payments, and payroll — often with a small team wearing multiple hats. It’s no surprise that accounting and bookkeeping mistakes creep in quietly, usually going unnoticed until a Federal Tax Authority (FTA) notice, a cash shortfall, or a rejected loan application forces the issue into the open. Most of these errors aren’t caused by negligence; they’re caused by systems that were never built to scale with the business. Below are the five mistakes we see most often across the SMEs, free zone companies, and trading firms we work with in Dubai, Sharjah, and Ajman — and what actually fixes each one.
1. Mixing Personal and Business Finances
This is the single most common mistake among founder-led businesses, particularly in the first two to three years of operation. A director pays a supplier from a personal card “just this once,” or draws cash from the business account to cover a personal expense, intending to reconcile it later. It rarely gets reconciled properly.
The consequences compound over time:
- Your profit and loss statement no longer reflects the real performance of the business
- VAT input recovery becomes harder to substantiate, since personal purchases mixed into business expense claims invite scrutiny
- Bank reconciliation takes hours longer every month because transactions can’t be cleanly categorised
- If you ever seek investment, a loan, or a company valuation, unclear financials become a red flag during due diligence
The fix: Open a dedicated business bank account from day one, issue a company card for all business spend, and route any owner withdrawals through a formal drawings or loan account rather than ad hoc transfers. A basic chart of accounts, even for a small trading company, makes this separation automatic rather than something you have to remember to do.
2. Falling Behind on VAT Return Filing and Payment
VAT compliance in the UAE runs on strict, unforgiving timelines, and the cost of missing them has recently changed. Under Cabinet Decision No. 129 of 2025, effective April 2026, the FTA restructured its VAT penalty regime: a first late VAT return submission now carries an AED 1,000 penalty, rising to AED 2,000 for repeated late filings within 24 months, and late payments now accrue interest at 14% per annum, calculated monthly from the day after the due date.
Businesses typically fall behind for one of three reasons: they lose track of which tax period they’re in, invoices arrive too late for the bookkeeper to process before the deadline, or a “nil” period gets skipped entirely because no transactions occurred. On that last point — the FTA treats a missed nil return the same as any other missed return, triggering the same late-filing penalty.
The fix: Set your VAT filing dates as recurring, non-negotiable calendar reminders — most businesses file quarterly, with the return due 28 days after the tax period ends. If your business has paused trading, either continue filing nil returns or formally deregister; don’t simply stop filing and hope it goes unnoticed. A monthly, not quarterly, bookkeeping cadence gives you a full three months of clean, categorised records by the time each VAT return is due, instead of a scramble in the final week.
3. Treating Corporate Tax as an Afterthought
UAE Corporate Tax is still relatively new for many business owners, and a lot of Dubai SMEs are still operating under the mistaken assumption that if they’re not making much profit, they don’t need to worry about it. That’s not how the law works. Registration is mandatory based on being a taxable person — not on whether you turned a profit — and even businesses electing Small Business Relief must still file a return.
The FTA has been direct about this: for companies with a financial year ending 31 December 2025, the corporate tax return and any tax due must be filed and paid within nine months of the end of the tax period — putting the deadline at 30 September 2026 — and companies claiming Small Business Relief are not exempt from this filing requirement, even though their return is simplified. Businesses relying on the relief still need to maintain records that let the FTA verify their revenue, taxable income, and continued eligibility.
The fix: Confirm your corporate tax registration status now if you haven’t already, and build a simple working paper that separates accounting profit from taxable profit throughout the year rather than trying to reconstruct it at year-end. If you’re a Qualifying Free Zone Person taxed at 0%, filing late doesn’t just trigger a penalty — it can put your entire 0% status at risk.
4. Weak or Inconsistent Record-Keeping
“We’ll organise the receipts later” is one of the most expensive sentences in small business accounting. Loose invoices, missing purchase orders, unreconciled petty cash, and inconsistent expense categorisation don’t just make monthly bookkeeping slower — they directly undermine your position if the FTA ever audits your VAT or corporate tax filings. The FTA can look back up to five years in a standard audit, or 15 years in cases involving fraud, which means today’s sloppy filing habit can become tomorrow’s liability.
Common gaps we see during onboarding audits include:
- Supplier invoices missing a valid Tax Registration Number (TRN)
- No clear trail linking a bank payment back to its supporting invoice
- Petty cash logs that stop being updated after the first few weeks
- Asset purchases and disposals never logged in a fixed asset register
The fix: Standardise how documents are captured the moment a transaction happens — not weeks later. Cloud accounting tools, or structured use of software like Tally Prime, let you attach the source document directly to the transaction, so nothing gets lost between the filing cabinet and the accountant’s desk. A clean, matched audit trail is also what turns a multi-week FTA review into a brief, low-stress one.
5. Relying on Founder-Led or Part-Time Bookkeeping for Too Long
Many Dubai businesses start with the founder doing the books in a spreadsheet, or a part-time bookkeeper coming in for a few hours a week. That model works fine at low transaction volume — and becomes a liability the moment the business scales, adds staff, opens a second bank account, or starts dealing with cross-border invoicing. The warning signs are consistent: bank reconciliations slipping by more than a month, VAT filings becoming rushed at the deadline, and management having no real-time view of cash flow because the books are always a few weeks behind reality.
This isn’t a criticism of founders — it’s a recognition that bookkeeping, VAT compliance, and corporate tax filing have each become specialised disciplines in the UAE over the past few years, and staying current with FTA rule changes (like the April 2026 penalty restructure) is close to a full-time job on its own.
The fix: Know the signal to change: if you can’t answer “what’s our current cash position?” within a few minutes, or if VAT filing is consistently a last-minute scramble, it’s time to bring in dedicated accounting and bookkeeping support — whether that’s an in-house hire or an outsourced firm that handles reconciliation, VAT, and tax filing as a coordinated system rather than separate fire drills.
Conclusion
None of these five mistakes are exotic — they’re the same patterns that show up, year after year, in businesses of every size across Dubai. What separates the businesses that get burned by them from the ones that don’t is usually just a system: a clean separation of personal and business funds, a filing calendar that doesn’t depend on memory, monthly reconciliation instead of quarterly panic, and someone qualified keeping an eye on both VAT and corporate tax obligations as they evolve.
If any of these five sound familiar in your own business, it’s worth getting a second set of eyes on your books before the next FTA deadline, not after a penalty notice arrives. Live Auditors & Chartered Accountants LLC works with businesses across Dubai, Sharjah, Ajman, and Abu Dhabi to clean up bookkeeping, manage VAT and corporate tax filings, and keep financial records audit-ready year-round.
Frequently Asked Questions
1. What are the most common bookkeeping mistakes small businesses make?
The most frequent ones are mixing personal and business finances, falling behind on VAT filing deadlines, poor or inconsistent record-keeping, treating corporate tax as optional, and outgrowing a part-time or founder-led bookkeeping setup without upgrading it.
2. What happens if a business files VAT late in the UAE?
Under the current penalty structure, a first late filing carries an AED 1,000 fine, rising to AED 2,000 for a repeat late filing within 24 months, plus late payment interest of 14% per annum calculated monthly from the day after the due date.
3. Do all UAE businesses need to register for corporate tax?
Yes. Registration is based on being a taxable person, not on profitability — a business with little or no taxable income, or one using Small Business Relief, still needs to register, obtain a registration number, and file a return by the deadline.
4. How often should a small business reconcile its bank accounts?
Monthly, at minimum. Quarterly reconciliation (done only ahead of VAT filing) tends to hide errors for weeks and makes year-end and tax filing far more time-consuming.
5. Can I do my own bookkeeping in Dubai or do I need an accountant?
It’s possible at very low transaction volumes, but once you’re VAT-registered, hiring staff, or approaching the corporate tax threshold, the compliance requirements typically outgrow what a founder can manage reliably alongside running the business.
6. What is Small Business Relief under UAE Corporate Tax?
It’s a relief available to businesses below a set revenue threshold that simplifies record-keeping and return requirements. Businesses electing it must still register for corporate tax and file a return — the relief simplifies the filing, it doesn’t remove the obligation.
7. How long should a business keep its financial records in the UAE?
As a general rule, at least five years, since that is the standard window the FTA can review during a VAT or corporate tax audit — longer in cases involving suspected fraud.
8. What is the penalty for late corporate tax filing in the UAE?
Late filing and underreporting penalties can include a fixed percentage of unpaid tax plus ongoing monthly interest — the exact structure depends on whether the error is self-disclosed or found by the FTA during an audit, which is why voluntary disclosure before an audit typically results in a lower penalty.
